How to Create a Family Business Succession Plan
A frequent complaint by next-generation members is that the senior generation never fully lets go of business tasks.
A frequent complaint by next-generation members is that the senior generation never fully lets go of business tasks.
Failing to properly plan for disability, death, or the ultimate transition of a family business can lead to disastrous financial consequences for both the business and the family.
People often overlook critical steps when they are doing their estate planning.
These vehicles let a family manage multiple interests, preserve parental control and protect assets from claims of creditors and divorcing spouses, among other benefits.
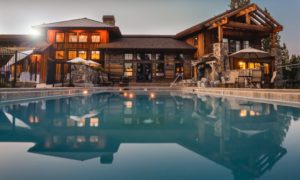
These vacation homes may also comprise a significant portion of the family’s wealth. Therefore, it’s understandable that homeowners want to pass their properties and family traditions to future generations.
According to the Exit Planning Institute of Ohio, recent studies show that over 60% of the current U.S. business market is owned by baby boomers (those born between 1946 and 1964), who are ready to exit or transition their business over the next 10 years.
If you’re planning to leave your heirs any sort of inheritance, you’re already giving them a valuable financial leg up.
In coming years, millions of Baby Boomers — those born between 1946 and 1964 — are expected to retire in the U.S. In fact, by some estimates nearly a quarter of this country’s population will be aged 65-or-older within a few decades.
An effective estate plan uses a collection of documents and teamwork to protect one’s assets and personal property. An effective estate plan also explains and carries intentions of how to pass control down to successors in the event of your absence.
Small business owners have their hands overflowing with issues, and they devote most of their time to matters related to the smooth running of the business. Having no time to think about other matters, they do not bother about estate planning for them.